

Vola: Cash Advance & Credit analysis by Appwee
I approached Vola: Cash Advance & Credit as a practical finance tool rather than a magic solution for running short on money. Its central promise is appealing: it can help eligible users seek an instant cash advance without a traditional credit check, while also bringing budgeting and spending awareness into the same place. In my experience, that combination is useful only when you understand the workflow and treat the advance as a temporary bridge, not as extra income.
Vola is a free finance app from Vola inc. It is available for Everyone, runs on Android 9 or later, and the current version is 3.4.15. The app has built a sizeable user base, with more than 500 thousand installs and a 4.7 average from roughly 11 thousand ratings. Those figures suggest that the idea resonates with many people, but they do not remove the need to check whether the service fits your own financial situation.
Where the experience usually gets stuck
The first point of friction is usually not the cash advance itself. It is the preparation needed before the app can make sense of a user's financial picture. A finance app cannot give useful budgeting or spending feedback if the information it relies on is incomplete, outdated, or connected in a way the user does not recognize. When something appears unavailable, delayed, or different from expectations, I would first treat it as a setup or account-information issue rather than immediately assuming the app is broken.
Another common misunderstanding is the phrase “no credit check.” That should not be read as “everyone receives money instantly” or “there are no conditions.” It describes an alternative to a traditional credit-check approach, not a guarantee of approval. Eligibility, timing, account status, and the details required during the application process still matter. I found it healthier to approach the advance screen as an application step with an outcome to review carefully, rather than as an automatic withdrawal of cash.
The budgeting side can also create confusion if you expect it to behave like a full bank account. Vola is best understood as a layer for accessing an advance and observing financial activity, not as a replacement for every banking function. If your goal is simply to move money between accounts, a bank app may be more direct. If your goal is to understand where your money goes and possibly bridge a short gap, Vola becomes more relevant.
A realistic example is a user whose paycheck arrives a few days after an essential bill. The app may be worth considering if the person can identify the exact shortfall, understands the repayment timing, and has a clear plan for the next deposit. The same person should pause if the gap happens every month, because repeated advances can hide a structural budget problem instead of solving it.
What I would check before requesting an advance
I would begin by confirming that the app is installed from the correct store and that the device meets the Android requirement. On an older phone, compatibility can be the reason an update or sign-in flow behaves strangely. I would also update the app before trying again, since the current release is 3.4.15 and an outdated installation can produce screens or errors that no longer match the active service.
Next, I would make sure the personal and financial information entered during setup is consistent. Small differences in names, account details, or other identifying information can create avoidable verification friction. I would not repeatedly submit slightly different versions of the same details; that can make it harder to tell whether the problem is a typo, a connection issue, or an eligibility result.
It is also worth checking the phone itself. A stable internet connection, enough free storage for an update, and a current operating system are simple checks, but they solve a surprising number of app problems. If the screen remains stuck, I would close and reopen the app, then restart the phone before attempting the process repeatedly.
The most useful setup habit is to separate technical troubleshooting from financial decision-making. First establish that the app opens, the account is accessible, and the information is entered correctly. Only then decide whether requesting an advance is sensible. Mixing those two questions can lead to a rushed borrowing decision simply because the user is frustrated by a loading screen.
How I would read the money-management tools
The spending and budgeting features are more valuable when used before an emergency. I would look at them during a normal week, identify recurring expenses, and compare the picture with the balance I expect to have before the next income payment. This creates a reference point. If I only open the app when I need cash immediately, I lose much of the benefit of the tracking side.
One practical workflow is to use the spending view as a short review after each pay cycle. I would look for subscriptions, delivery purchases, transport costs, and small repeated transactions that are easy to overlook individually. The goal is not to eliminate every enjoyable expense; it is to find the items that explain why a supposedly manageable week keeps ending with a shortfall.
There is a trade-off here. A dedicated budgeting app may offer deeper planning, categories, or long-term goal tools, while a bank app may show transactions with fewer layers between the user and the account. Vola’s appeal is the connection between spending awareness and access to a cash advance. That convenience is helpful for someone who wants both in one finance app, but it may feel limited to a person seeking detailed financial planning.
Recovering when the workflow fails
If an advance request does not progress, I would avoid tapping the same button over and over. Repeated attempts can make the situation less clear, especially when the first request may still be processing. Instead, I would note the exact screen where the process stopped, read any message carefully, and return later after checking the connection and account information.
If the app opens but transactions or spending information look incomplete, I would first consider timing. Financial information may not appear at the same moment as activity in the bank account. I would compare the app with the original banking source and avoid making a borrowing decision based on a partial picture. A missing transaction can make the available balance appear more comfortable than it really is.
If sign-in fails, I would use the normal account-recovery path rather than creating a second account. A duplicate account can complicate access and make it harder to understand which profile contains the relevant history. I would also check whether the issue affects only Vola or other apps, because a broader network or device problem needs a different fix.
When an update appears unavailable, I would confirm the device version, free space, and store connection. Since Android 9 is the minimum operating system, a phone below that requirement is not a good candidate for troubleshooting through repeated reinstalls. On a compatible device, restarting the store app and the phone can help, but I would avoid deleting account-related information unless I understand what will be removed locally.
For a financial product, screenshots and notes can be useful when contacting support, provided they do not expose sensitive account numbers, passwords, or identity documents. I would record the time of the attempt, the wording of the error, and whether the problem happened on mobile data or Wi-Fi. That gives support something more useful than “it does not work,” while keeping private information protected.
When the app is not the cause
Some apparent failures are really consequences of the user's bank, device, or financial circumstances. A bank connection can be delayed, an account can have restrictions, or a deposit can arrive later than expected. Vola cannot make an external institution update faster, and an advance cannot fix a balance that is already committed to several upcoming payments.
This is why I would compare the app's information with the bank's own record before requesting money. If the figures disagree, the safest assumption is that the situation needs clarification. Borrowing against an optimistic balance is a risky mistake, particularly when the account is already close to its limit.
There is also a difference between technical access and eligibility. A perfectly functioning app can still show that a user cannot proceed with an advance. That is not necessarily a software defect. The sensible response is to read the result, avoid trying to bypass it with inaccurate information, and consider whether another legitimate option is more appropriate.
For urgent essentials, I would compare the likely cost and timing of an advance with alternatives such as asking a provider for a payment arrangement, using an existing emergency fund, or speaking with a trusted person. A conventional bank overdraft or credit product may be more suitable for someone who needs a larger, longer-term facility and can compare its terms carefully. On the other hand, those alternatives may involve credit assessment or conditions that make Vola attractive to a user seeking a different route.
Who will benefit most from Vola?
I see the strongest fit in someone with a temporary cash-flow mismatch, a reliable plan for incoming money, and enough discipline to inspect repayment consequences before accepting an advance. The budgeting and spending view can add value for a person who wants to understand the cause of the shortfall rather than simply cover it.
It may also suit someone who does not want to use a traditional credit-check route and prefers a free app that combines short-term access with money tracking. The key word is temporary. If the same request is needed repeatedly, the app should become a prompt to rebuild the monthly budget, not a permanent part of it.
I would be cautious about recommending it to anyone already juggling several forms of debt, anyone who cannot predict how the next income payment will be used, or anyone looking for a long-term borrowing solution. It is also not the best choice for users who want advanced investment tools, comprehensive financial planning, or a complete replacement for their bank.
Questions I would answer before installing it
Is it really free? The app itself is free to install, but that does not mean every financial transaction or advance is costless. I would read the terms shown during the relevant process and consider the total effect on the next payment cycle before accepting anything. “Free app” and “free borrowing” are not interchangeable ideas.
Does no credit check mean approval is guaranteed? No. It means the service is presented without a traditional credit check, but users should still expect an eligibility process and should not assume every request will succeed. I would only plan around money once the app clearly confirms the outcome.
How quickly will money arrive? The phrase “instant cash advance” sets an expectation of speed, but real timing can depend on account details, processing, and outside institutions. I would not schedule a bill around an advance until the app shows that it has been completed and the receiving account reflects it.
Can it replace my bank or budgeting software? Not completely. It can combine an advance workflow with budgeting and spending awareness, which is its distinctive convenience. A bank remains the better place for core account management, while a specialized budgeting tool may be better for detailed long-term planning.
What should I do if the numbers do not add up? Stop before requesting money, compare the app with the bank's own records, check pending payments, and resolve the discrepancy first. That small pause is one of the most valuable habits when using any cash-advance service.
My practical verdict
After looking at the complete workflow, I think Vola is most convincing as a focused bridge for a short, clearly understood cash gap. Its free access, spending tools, and alternative approach to credit checking make it more interesting than a simple borrowing screen. The rating of 4.7 and its broad adoption also indicate that many users find the overall concept useful, although personal circumstances matter more than popularity.
My main reservation is behavioral rather than technical. Easy access to a cash advance can feel like a solution when the real issue is that regular expenses exceed regular income. The app can help reveal that pattern through spending tracking, but it cannot replace a sustainable budget. I would use the tracking features routinely, treat an advance as exceptional, and review the next payment cycle before making another request.
For someone facing a one-off timing problem and willing to read each step carefully, Vola is worth considering. For someone seeking long-term credit, sophisticated financial planning, or certainty that money will arrive regardless of circumstances, I would choose a different option. My recommendation is therefore measured: install it if the combination of cash-flow support and spending awareness matches your needs, but keep the decision anchored to what you can repay comfortably rather than to what the app may make available.
Gallery
Vola: Cash Advance & Credit Pros and Cons
- Fast access to small cash advances when unexpected expenses arise.
- Simple application process managed entirely from a mobile device.
- May help cover bills between paychecks without using a credit card.
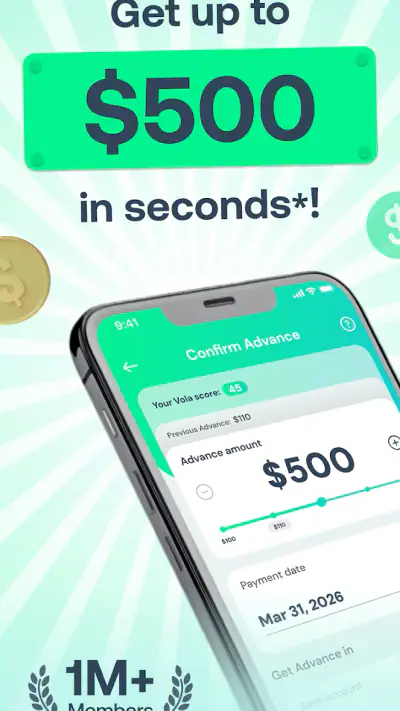
- Repayment dates and advance details are clearly shown in the app.
- Useful budgeting features can help users monitor upcoming cash needs.
- Advance limits may be low for larger emergency expenses.
- Fees or optional tips can make borrowing more expensive than expected.
- Eligibility and available amounts may change after each application.
- Automatic repayment could strain your account on the due date.
- Not available in every state or for all types of bank accounts.
Vola: Cash Advance & Credit Frequently Asked Questions
What is Vola: Cash Advance & Credit, and how does it work?
Vola: Cash Advance & Credit is a financial app designed to help eligible users access funds before their next paycheck and monitor aspects of their financial health. After creating an account and connecting a supported bank account, the app reviews information such as income and account activity to determine available features and eligibility. Approval, advance amounts, fees, and delivery times can vary by user.
Who can use Vola, and what information is required to apply?
Eligibility depends on factors such as your age, location, income, banking history, and whether your financial institution is supported by the app. During registration, Vola may request personal identification details, employment or income information, and permission to connect a bank account. Users should review the current eligibility requirements and privacy policy carefully, because meeting basic requirements does not guarantee approval or access to every feature.
How much money can I receive through Vola, and when will it arrive?
The amount available through Vola is determined individually and may depend on your income, account activity, repayment history, and other eligibility criteria. Delivery speed can also differ depending on the selected transfer method, bank processing times, weekends, and holidays. Before confirming a request, check the app for the exact advance amount, expected arrival date, applicable fees, and any optional expedited-delivery charges.
Does Vola charge fees, interest, or require a subscription?
Costs can depend on the product and services available to your account. Depending on the current terms, users may encounter membership or subscription charges, transfer fees, optional expedited funding costs, or other disclosed expenses. A cash advance is not necessarily free simply because it does not use traditional interest. Always read the final confirmation screen and Vola’s fee agreement before accepting an advance or starting a paid plan.
What should I know about repayment, privacy, and account security?
Before using Vola, make sure you understand when repayment is due and how the app may collect the amount owed, including any authorized automatic debit from a linked account. Late or unsuccessful repayment could affect access to future services and may result in additional consequences under the applicable agreement. Because the app handles sensitive financial data, use a secure device, enable available security features, and review permissions, data-sharing practices, and account-deletion options.














